The National Response to COVID-19: A Brief Overview
In early 2020, the nation was in a state of emergency due to the COVID-19 pandemic. Recognizing the risk of mass evictions as a result of the pandemic, many state and local governments enacted a moratorium on residential evictions. These moratoria effectively denied landlords the right to pursue an unlawful detainer (eviction) action - the only legal means of removing tenants for failure to pay rent.
Washington State's Eviction Moratorium and the ERPP Initiative
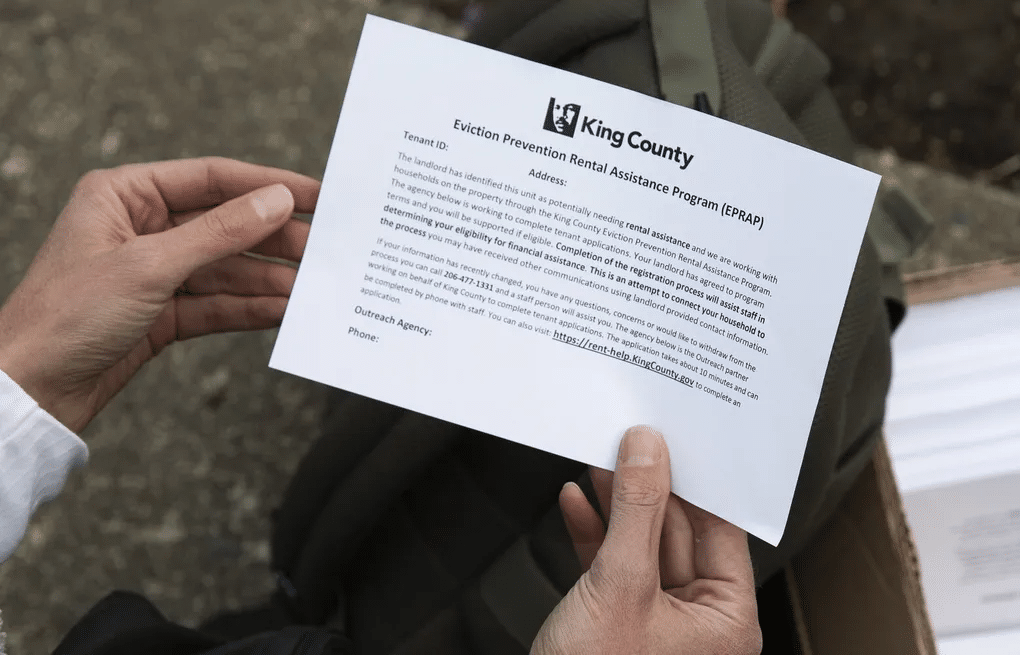
In Washington state, an eviction moratorium was in effect from March 18, 2020, through October 31, 2021. Following the end of the moratorium, the Washington state legislature passed E2SSB 5160 authorizing the establishment of an Eviction Resolution Pilot Program (ERPP) in any county in Washington state. The ERPP was designed to facilitate dispute resolution between landlords and tenants, by connecting them with a dispute resolution specialist and resources such as rental repayment assistance. Once the eviction moratorium ended on November 1, 2022, six counties in Washington state elected to participate in the ERPP: King, Pierce, Snohomish, Clark, Spokane, and Thurston. Each program established a local Dispute Resolution Center (DRC) and operated pursuant to a standing order issued by the local superior court.
Pursuant to the ERPP, landlords in participating counties were required to provide tenants with an ERPP Notice, advising tenants of their rights under the ERPP, and a proposed repayment plan for outstanding rent amounts owed. Upon receiving an ERPP Notice and proposed repayment plan, tenants had 14 days to negotiate a proposed settlement with their landlord via the local DRC. In circumstances where the landlord and tenant failed to come to an agreement during the 14-day period, or the tenant breached the agreement, the landlord was then authorized to send the tenant a 14-day notice to pay or vacate.
The End of ERPP and Its Impact
The ERPP ended by statute on July 1, 2023. Dispute Resolution Centers statewide reported that over 78,000 cases were closed and completed during the life of the program, and 73% of these cases closed because the landlord and tenant reached an agreement. Now that the program has ended, landlords are no longer required to provide tenants with an ERPP Notice or a proposed repayment plan before proceeding with an unlawful detainer for unpaid rent.
The end of the ERPP marks the end of all remaining COVID-19 eviction protections for tenants. However, some counties in Washington state still maintain permanent eviction moratoriums during parts of the year. In Seattle, City Council Ordinance 126041 creates a defense to eviction for tenants who would have to vacate their housing between December 1 through February 28 each year. Additionally, Seattle City Council Ordinance 126369 creates a defense to evictions for anyone in school, with children in school, or working at a school during the City of Seattle Public school year, which is generally the beginning of September through mid-June.
Need Legal Assistance? Contact Lether Law Group
Lether Law Group has attorneys licensed and actively participating in eviction proceedings in Washington state. To the extent that you have any questions about Washington landlord-tenant law or eviction moratoria, please feel free to contact us by phone at (206) 467-5444 or via email at info@letherlaw.com.
Thanksgiving is a time to spend with family and friends and celebrate all that we are thankful for. It is also a time for a cornucopia of potential insurance claims. Thanksgiving-related insurance claims can run the gamut from auto accidents, to slip-and-falls, fire losses, and even business losses.
This year, it is estimated that 54.6 million people will travel more than 50 miles for their Thanksgiving celebrations, which greatly increases the risk of an auto accident or other travel-related insurance claim. In addition, the National Fire Protection Association (“NFPA”) has noted that Thanksgiving is the leading day of the year for home cooking fires in the United States.[1] In fact, the NFPA has reported that home cooking fire reports increase over 200% on Thanksgiving Day versus the daily average for the rest of the year.[2]
Increased risks of insurance claims are also not limited to homeowners and/or auto claims and the risks do not end on Thanksgiving Day. Millions of Americans will also venture out on Black Friday to take advantage of the many deals that can be found on the biggest shopping day of the year. This leads to increased exposure for businesses from parking lot accidents, slip-and-falls, miscellaneous property damage, and theft.
The increased number of losses over the Thanksgiving Weekend also results in an uptick in insurance claims under auto policies, homeowners policies, and business insurance policies. This means that insurers need to be ready to staff and handle a potentially large volume of new claims, both first-party and third-party, in the days and weeks surrounding the Thanksgiving Holiday.
With these increased risks in mind, the Lether Law Group Family encourages everyone to use extra caution as you enjoy time with family and friends and/or as you venture out on Black Friday.
If something unexpected should occur or if you need advice for post-Thanksgiving-related insurance claims, please keep in mind that the attorneys at Lether Law Group have over 33 years in combined experience in advising insurers and defending first and third-party claims. This includes providing coverage advice and defending large property losses, catastrophic accident injuries, and other spontaneous and unexpected claims. Please feel free to contact us at any time if you would like to discuss any Thanksgiving-related claims or any other matter.
On October 17, 2022. The United States Court of Appeals for the Ninth Circuit issued additional Opinions regarding COVID-19 Business Interruption claims.
In McCulloch, et al v. Valley Forge Ins. Co., et al¸ No. 21-35520, 2022 U.S. App. LEXIS 2860, 2022 WL 9830777 (9th Cir. Oct. 17, 2022), the Court affirmed a summary judgment ruling from the Western District of Washington dismissing claims by several dentists/dental clinics. The Plaintiffs argued that their claims were improperly dismissed because they asserted the claims resulted from “direct physical loss of or physical damage to” their insured premises. The Ninth Circuit disagreed.
While the appeal was pending, the Washington State Supreme Court issued its ruling in Hill & Stout, PLLC v. Mutual of Enumclaw Ins. Co., 515 P.3d 525 (2022), in which the Supreme Court held that “loss of intended use of property” and “loss of business income” from COVID-19 orders did not qualify for insurance coverage as “direct physical loss of or damage to property.” As a result, the Ninth Circuit dismissed the breach of contract/direct physical loss claim. The Court also dismissed Plaintiff’s claims that they were entitled to coverage under the policies’ civil authority coverage because there was no evidence that the Washington State Governor’s orders were in response to any actual physical property damages. Therefore, the Ninth Circuit concluded that the Hill & Stout Opinion also precludes coverage.
In addition, the Ninth Circuit dismissed the appeal for extra-contractual claims. With respect to the extra-contractual claims, certain Plaintiffs argued that the insurer unreasonably denied their claim and failed to conduct a reasonable investigation of the claims. The Ninth Circuit rejected both arguments. Specifically, the Court noted that the unreasonable denial claim first required a showing of an incorrect denial of the claim. Because the claim was properly denied, the extra-contractual claim failed. The Court rejected the unreasonable investigation argument because “the insurer’s denial of coverage was based on a legal interpretation of the policy. [As a result,] [t]here was no need for factual investigation…”
In Hot Yoga, Inc. v. Philadelphia Indem. Ins. Co.¸No. 21-35806, 2022 U.S. App. LEXIS 28674, 2022 WL 9732180 (9th Cir. 2022), the Ninth Circuit similarly affirmed dismissal of contractual claims based on the Washington State Supreme Court’s Opinion in Hill & Stout. In addition, the Court held that the policy’s virus exclusion, precluding coverage when a virus initiates the causal chain that led to the cause of any claimed loss, barred coverage.
The Ninth Circuit also rejected the insured’s arguments regarding its extra-contractual claims. The insured argued that the district court erred in dismissing extra-contractual claims premised on the insurer allegedly “misrepresenting the pertinent policy language and preemptively denying the claim without any investigation.” The Ninth Circuit held that the claims necessarily failed because the policy did not provide coverage.
As we previously opined, it is clear that the Washington State Supreme Court’s decision and reasoning in Hill & Stout is having a substantial impact on pending COVID-19 BI claims in Washington. We anticipate that there will be several other similar rulings in the near future.
If you have any questions about the above Ninth Circuit cases and how the Hill and Stout case will continue to impact COVID-19 BI claims and cases, please give us a call.
Kevin J. Kay
Shareholder
Kevin is a graduate of Pacific Lutheran University and Seattle University School of Law. He is licensed to practice in the state and federal courts of Washington and admitted to practice before the Ninth Circuit Court of Appeals. In addition, Kevin has appeared pro hac vice in courts in Louisiana and California. Kevin has represented insurers and insureds in coverage for 16 years. These claims involve personal and commercial auto policies, commercial general liability, professional liability, and E&O insurance. Kevin has also advised and represented risk pools, insurers, and insured in matters ranging from automobile/bus accidents to catastrophic landslides. His practice also includes construction defect disputes, personal injury claims, commercial leases, and significant property damage disputes.
The rapid spread of COVID-19 throughout the United States and resulting governmental shut-down orders have sparked a large increase in business interruption claims and subsequent litigation. While “direct physical loss” and “necessary suspension” policy language have been addressed in most jurisdictions, the less commonly litigated terms of civil authority coverage and virus exclusions are the subject of debate in many courts across the country. The following is a summary of notable rulings on COVID-19 business interruption coverages:
In re: COVID-19 Business Interruption Protection Insurance Litigation, United Statees Judicial Panel on Multidistrict Litigation, MDL No. 2942, 2020 U.S. Dist. LEXIS 144446: The Panel denied the plaintiffs’ motion to transfer and consolidate 263 cases across 48 districts into a single industry-wide business interruption coverage case. The Panel found that consolidation was inappropriate because differences overwhelmed any common factual questions – there was no common defendant, different policy forms, and a diverse group of plaintiffs located throughout the United States. Moreover, the Panel found that consolidation would be inefficient for all parties and courts involved.
10E, LLC v. Travelers Indem. Co., United States District Court for the Central District of California Case No. 2:20-cv-04418-SVW-AS, 2020 U.S. Dist. LEXIS 156827: The court granted Travelers’ Motion to Dismiss, interpreting “direct physical loss” to require “the permanent dispossession of something” as opposed to a temporary restriction of the use of property. The 10E court found that the plaintiff-restaurant was not entitled to business interruption loss or civil authority coverage arising from governmental orders restricting restaurants to take-out and delivery due to COVID-19.
Gavrilides Management Co. v. Michigan Insurance Co., Michigan Circuit Court Case No. 20-258-CB-C30: The court granted Michigan Insurance Company’s motion to dismiss after finding that a loss of income due to orders limiting a restaurant’s operations to take-out and delivery in response to COVID-19 did not satisfy the requirement of physical loss of or damage to property. The Gavrilides court stated that “physical alteration to or physical damage or tangible damage to the integrity of the building” was required for coverage.
Malaube, LLC v. Greenwich Ins. Co., United States District Court for the Southern District of Florida Case No. 20-22615-Civ, 2020 US Dist LEXIS: Magistrate Judge Edwin Torres recommended granting Greenwich Insurance Company’s Motion to Dismiss COVID-19 Business Interruption claims brought by a restaurant. Where government orders prohibited indoor dining but allowed delivery and take-out orders, Judge Torres found that no “direct physical loss or damage” occurred because the government orders never made the plaintiff’s restaurant uninhabitable or substantially unusable.
Rose’s 1, LLC v. Erie Ins. Exch., District of Columbia Superior Court Case No. 2020 CA 002424 B, 2020 D.C. Super. LEXIS 10: The court granted summary judgment after finding that government orders restricting business operations do not constitute “direct physical loss.” The court found that that the government’s orders did not cause any “direct” change to properties, that the orders did not have any “effect on the material or tangible structure of the insured properties,” and the orders did not constitute a “loss” because they did not have any “direct physical intrusion on to the insured property.”
Diesel Barbershop, LLC, v. State Farm Lloyds¸ United States District Court for the Western District of Texas Case No. 5:20-CV-461-DAE, 2020 U.S. Dist. LEXIS 147276: The court granted State Farm’s motion to dismiss, finding that business interruption coverage required tangible injury to property and upholding the policy’s virus exclusion. Specifically, the court found that the shut-down orders were a sequential result of the presence of COVID-19, and therefore, “the primary root cause” of Plaintiffs’ business closure.
Social Life Magazine, Inc. v. Sentinel Ins. Co. Ltd., United States District Court for the Southern District of New York No. 20 Civ. 3311 (VEC): The court denied plaintiff’s motion for preliminary injunction because COVID-19 does not cause physical damage to property, rather, “it damages a person’s lungs.”
Optical Services USA, et al. v. Franklin Mutual Insurance Company, New Jersey Superior Court Case No. BER-L-3681-20: The court denied Franklin Mutual’ s motion to dismiss, finding that plaintiffs should have the opportunity to engage in issue-oriented discovery to fully establish the record regarding direct covered losses and to amend their complaint accordingly. The court also found that Franklin Mutual failed to provide any controlling legal authority supporting their interpretation of “direct physical loss,” admitting that the New Jersey legal authority addressing this issue was limited.
Martinez v. Allied Insurance Company of America, United States District Court for the Middle District of Florida, Case No. 2:20-cv-00491-FtM-66NPM: The court granted Allied’s motion to dismiss, upholding the policy’s virus exclusion. The court found that plaintiff failed to assert that his loss or damage was due to a “covered cause of loss.” Rather, the court found that because the plaintiff’s damages resulted from COVID-19, neither the governmental orders narrowing plaintiff’s dental services nor the disinfection of the dental office constituted a “covered cause of loss” pursuant to the policy’s virus exclusion.
Studio 417, Inc., et al. v. The Cincinnati Insurance Company, United States District Court for the Western District of Missouri Case No. 20-cv-03127-SRB, 2020 U.S. Dist. LEXIS 147600: The court denied Cincinnati’s motion to dismiss, finding that the plaintiff had adequately stated a claim for direct physical loss and claims under the policy’s civil authority, ingress and egress, and dependent property coverages. Specifically, the court found that plaintiff’s adequately alleged a causal relationship between COVID-19 and their losses – that COVID-19 “is a physical substance” that attached to and deprived Plaintiff’s of their property, making it “unsafe and unusable”.
Turek Enterprises, Inc. v. State Farm Mutual Automobile Insurance Company, et al., United States District Court for the Eastern District of Michigan Case No. 20-11655, 2020 U.S. Dist. LEXIS 161198: The court granted State Farm’s motion to dismiss, finding that “direct physical loss” required tangible damage and that coverage was otherwise precluded by the virus exclusion. Specifically, the governmental orders and plaintiff’s business interruption losses resulting therefrom “would not have occurred but for COVID-19.”
Lether Law Group currently represents several national insurers in COVID-19 business interruption litigation in state and federal courts in Washington, Oregon, California, and Pennsylvania. If you have questions about any state-specific requirements which have been enacted due to the COVID-19 pandemic or general questions in regard to pending insurance claims and compliance with any regulatory requirements, please feel free to contact our office.
The above article is an opinion based on various resources such as industry knowledge and is not to be construed as legal advice or to be used as such. If you require legal advice or would like to inquire further about the information contained in this article, please feel free to contact our office directly.
As the COVID-19 crisis continues to impact every aspect of our personal and professional lives, Lether Law Group is continuing to monitor any and all new developments that may impact our clients. To the extent that you have any questions or would like to discuss any potential issues related to COVID-19 and its impacts, please feel free to contact us at any time.
One of the issues that has been persistent since the inception of the crisis is whether the commercial impacts of COVID-19 should be remedied by federal, state, and local governments or through the private sector. Specifically, and as we have previously reported, many governmental entities have called on commercial property insurers to extend Business Interruption and Civil Authority coverage to businesses closed or limited due to the COVID-19 outbreak.
However, as has now been widely chronicled, Business Interruption coverage is only available due to necessary suspension of operations due to physical damage to the insured premises. Moreover, many modern commercial property forms contain an exclusion for any losses caused by the presence, proliferation, or spread of a virus.
As a result, under most circumstances surrounding COVID-19 related business shutdowns, there would likely not be coverage available to the insured. However, that does not mean that there is no coverage available in every circumstance.
Given what appears to be clear and unambiguous policy language concerning Business Interruption coverage, what is emerging is a series of bad faith claims against insurers that are summarily denying Business Interruption claims without conducting any investigation or even in some instances, not even with a written explanation of the coverage position. Policyholders nationwide are bringing bad faith claims alleging cursory, over-the-phone denials of these claims.
As we have previously noted, we are not aware of any insurance commissioner in any United States jurisdiction that has suspended the Unfair Trade Practices Act regulations during the COVID-19 epidemic. To the contrary, rather than suspending insurance claims regulations, insurance commissioners are taking steps to ensure that those regulations are followed. By way of example, on April 14, 2020, the insurance commissioner for the State of California issued a Notice to insurers advising of complaints about cursory denials and even refusals to open Business Interruption claims. The Notice then provided as follows:
Upon receipt of a notice of claim, the insurer is required to provide the policyholder with the necessary forms, instructions, and reasonable assistance, including but not limited to, specifying the information the policyholder must provide in connection with the proof of claim and begin any necessary investigation of the claim. (Regulations, section 2695.5(e)(2).) Thereafter, every insurer is required to conduct and diligently pursue a thorough, fair, and objective investigation of the reported claim, and is prohibited from seeking information not reasonably required for or material to the resolution of a claim dispute before determining whether the claim will be accepted or denied, in whole or in part. (Regulations, section 2695.7(d).)
(emphasis added)
The California OIC’s Notice demonstrates the conflict between the public and private sectors. The OIC cannot force insurers to provide coverage so the agency is left to issue stern Notices to insurers requiring the insurers to follow the law.
Ultimately, pronouncements such as that by the California OIC do not really change anything. Insurers are still required to comply with claim handling regulations and act in good faith. That includes promptly responding to pertinent communications, conducting a reasonable investigation, and providing the insured with a written explanation of the coverage decision, etc.
Once again, if you have any questions or concerns relating to COVID-19 related claim or any other issues, please feel free to contact Lether Law Group at any time.