1-206-467-5444 info@letherlaw.com

Washington Court Reaffirms Insurers’ Right to Participate in Reasonableness Hearings

On October 28, 2024, the Washington State Court of Appeals considered the validity of a reasonableness determination obtained without proper notice to the liability insurer, and held that without proper notice, the liability insurer is not bound to the reasonableness determination. This ruling further solidified the procedures set forth allowing liability insurers the opportunity to participate in reasonableness hearings in Washington State.

In Hawkins v. Miguel et al., Shelley Hawkins and Edwin Miguel entered into a covenant judgment settlement, establishing Miguel’s liability and assigning Miguel’s bad faith claims against his employer’s insurer, ACE American Insurance Company (ACE) to Hawkins. Thereafter, Hawkins obtained a ruling from the Court that the amount of the covenant judgment settlement was reasonable. However, in obtaining this reasonableness determination, Hawkins did not provide notice of the reasonableness hearing to ACE, and therefore did not provide ACE with the opportunity to be heard at the hearing.

Hawkins proceeded to obtain judgment against ACE on the assigned claims. In determining the validity of the reasonableness determination, in light of the fact that ACE was not provided notice and opportunity to be heard regarding the settlement amount, the Court of Appeals ruled that ACE was not bound by the reasonableness determination.

On June 23, 2021, Miguel entered into a settlement agreement for 41.5 million, with judgment interest at 12%. Thereafter, Hawkins filed a motion for determination of reasonableness with respect to the June 23, 2021 settlement agreement and for judgment thereon. On July 20, 2021, the superior court granted Hawkins’s motion to find the settlement reasonable. On August 12, 2021, Hawkins and Miguel mailed a 20 day pre-suit IFCA notice to ACE, and thereafter filed a corrected amended complaint, asserting claims against ACE for negligence, violation of IFCA, and breach of the duty of good faith on October 1, 2021. Pursuing litigation, the superior court found that as a matter of law, ACE breached the insurance policy, breached the duty of good faith, and violated IFCA. The court further struck ACE’s affirmative defense that Miguel failed to comply with the policy’s conditions to the prejudice of ACE. The Court awarded enhanced damages under IFCA, as well as attorney fees and costs under Olympic Steamship v. Centennial.  The superior court entered judgment for Hawkins against ACE in the amount of $5,443,200.00, and an additional judgment of $232,195.60 for attorney fees. ACE thereafter appealed.

On appeal, ACE argued that the superior court’s imputation of the reasonableness determination to ACE violated ACE’s right to due process as it was not given notice of the hearing. The Court considered what is meant by the insurer’s having been given the “opportunity to be involved in a settlement” pursuant to Mutual of Enumclaw Insurance Company v. T & G Construction, Inc. 165 Wn.2d 255, 267, 199 P.3d 376 (2008). The Court noted that it is undisputed that Hawkins and Miguel did not give ACE notice of the settlement or of their intent to obtain a reasonableness determination until after they had already presented their motion and obtained the order.

The Court relied on the long-settled rule that an insurer is “bound by the findings, conclusions, and judgment entered in the action against the tortfeasor when it has an opportunity to intervene in the underlying action.” This reflects the notion that where an insurer is given notice but fails to defend where there is an obligation to do so is bound by a litigated judgment on the liability indemnified.

Turning directly to reasonable settlements, the Court notes that Washington applies a corollary rule of equal antiquity that states an insurer is bound by a reasonable settlement, reasonable meaning made without fraud or collusion. The Court notes that reasonableness is especially relevant to a covenant settlement, which involves three features: (1) a stipulated or consent judgment between the plaintiff and insured, (2) a plaintiff’s covenant not to execute on that judgment against the insured, and (3) an assignment to the plaintiff of the insured’s coverage and bad faith claims against the insurer. Once the reasonableness of a stipulated judgment is established, the amount of said judgment becomes the presumptive measure of that component of damages in a later bad faith actions. Simply put, the reasonableness of a stipulated or covenant judgment plays a large role in a later bad faith suit.

In order to protect the integrity of reasonable settlements, and therefore avoid unreasonable settlements, Washington courts have adopted a nine factor test to determine the reasonableness of a settlement amount. Most notable here is the Supreme Court’s emphasis of these factors, especially where “the insurer has notice of the reasonableness hearing and has an opportunity to argue against the settlement’s reasonableness.” Besel v. Viking Ins. Co. of Wisconsin, 146 Wn.2d 730, 739, 49 P.3d 887 (2002). The court notes the importance of allowing an insurer to be heard on reasonableness where the court will bind the insurer to said settlement.  In conclusion, the Court clearly concluded the importance that an insurer is given notice of the reasonable hearing itself in order to be bound by its outcome, not merely notice that the underlying suit had been commenced.

In finding that ACE was not bound by the reasonableness determination, the Court of Appeals stated:

Because Hawkins and Miguel did not give ACE notice of the settlement and the reasonableness hearing, the reasonableness determination cannot bind ACE consistent with due process. As a result, as to ACE, there has been no binding determination that the settlement was reasonable, and there is no current basis on which to bind ACE to the settlement amount, or find it liable for that amount, interest, or treble damages. Therefore, the May 3, 2023 summary judgment order, judgment against ACE finding it liable for the consent judgment, and judgment against ACE finding it liable for treble damages under IFCA must be reversed to that extent.

The Hawkins opinion emphasizes the importance of procedure in covenant judgments and reasonableness hearings. An insured is expressly required to provide notice of a reasonableness hearing to the insurance company, however it is of even more importance that the insurer appears and participates in the reasonableness hearing in good faith.

The attorneys at Lether Law Group have in excess of thirty-five years experience in insurance coverage litigation, including but not limited to covenant judgments, reasonableness hearings and litigation insurance disputes in the state of Washington. Please do not hesitate to contact our office if you have any questions regarding the Hawkins opinions or any other insurance matter.
Washington State Supreme Court Clarifies Law on “Reasonable Investigation” and Determination of “Reasonable” Charges for Personal Injury Protection Claims

On February 15, 2024, the Washington State Supreme Court issued its decision in Schiff v. Liberty Mutual Fire Insurance Company, et al., Case No. 101576-3, which examined “… what an insurer must do to meet the ‘reasonable investigation’ requirement and the requirement to pay ‘all reasonable and necessary’ medical expenses” under Washington’s Personal Injury Protection (“PIP”) statutes and Washington law.

The decision arose out of a suit filed by Dr. Stann Schiff alleging that the insurers’ practice of reducing provider bills based on computer-generated calculations violated Washington law.  It was undisputed that Liberty Mutual Fire Insurance Company and Liberty Mutual Insurance Company (collectively “Liberty”), used a third-party database called FAIR Health to determine reasonableness of a medical provides charges when Liberty received medical bills from an insured under either a PIP or a MedPay (supplemental medical payment coverage) claim. [1]

The trial court denied both parties’ attempts at summary judgment and the Court of Appeals accepted discretionary review. The Court of Appeal, relying on its prior holding in Folweiler Chiropractic, P.S. v. American Family Insurance Co, 5 Wn. App. 2d 829, 429 P.3d 813 (2018) reversed the trial court’s denial of Dr. Schiff’s motion. The Court of Appeals reasoned, based on the Folweiler decision, that: 1) it was an unfair practice under the Washington Consumer Protection Act (“CPA”) to not conduct an individualized assessment of a medical bill; and that 2) RCW 48.22.095(1)(a) and RCW 4.22.005(7) required an individualized assessment.

The database provided information for an insurer to compare charges for specific medical treatments in a geographical area and to determine the percentiles of those charges.  Liberty apparently had an established practice of paying 100% of a medical provider’s bill if it was below the 80th percentile for the procedure/treatment in the geographical area. However, if the bill exceeded the 80th percentile, Liberty would reduce the charges to the 80th percentile charge and pay that amount. It was undisputed that Liberty did not conduct individualized investigations with respect to the bills at issue, but instead relied upon 80th percentile information from the database.

The trial court denied both parties’ attempts at summary judgment and the Court of Appeals accepted discretionary review. The Court of Appeal, relying on its prior holding in Folweiler Chiropractic, P.S. v. American Family Insurance Co, 5 Wn. App. 2d 829, 429 P.3d 813 (2018) reversed the trial court’s denial of Dr. Schiff’s motion. The Court of Appeals reasoned, based on the Folweiler decision, that: 1) it was an unfair practice under the Washington Consumer Protection Act (“CPA”) to not conduct an individualized assessment of a medical bill; and that 2) RCW 48.22.095(1)(a) and RCW 4.22.005(7) required an individualized assessment.

The Supreme Court rejected the Court of Appeals’ analysis and overturned the Court of Appeals. In doing so, the Supreme Court effectively also overturned the Folweiler decision’s individualized assessment requirement. In discussing the Folweiler decision, the Supreme Court stated and held as follows:

Though the Court of Appeals cited to the relevant statutes and regulations, it failed to explain how they mandate an inquiry into the qualifications of the medical provider and did not cite any case to bolster its interpretation. The PIP statutes and the insurance code do not have any express requirement that the insurers look specifically at the qualifications of a medical provider to determine the reasonableness of the charge.

Schiff Opinion at 12 (emphasis added).

Instead, the Supreme Court held that the insurance code: 1) places the responsibility on an insurer to determine whether to deny, limit, or terminate medical benefits if the insurer determines the claim is not reasonable or necessary; 2) that the code tasks insurers to conduct their own reasonable investigation; 2) that the code requires insurers to create their own reasonable standards for promptly investigating a claim.

After reviewing the Washington Administrative Code (“WAC”) and the properties of the FAIR Health database, the Supreme Court held that “Comparing charges for the same treatment in the same geographic area is relevant to the determination of reasonableness.” Schiff Opinion at 14.

As a result of this conclusion, and in light of out-of-state authority addressing the same issues, the Supreme Court ultimately held in favor of Liberty as follows:

We hold that the 80th percentile practice and the use of the FAIR Health database is not unfair or unreasonable and does not violate the CPA or the PIP requirements to establish standards under which reasonable charges for medical procedures are determined.

Schiff Opinion at 16.

The Schiff decision effectively overturns the Folweiler decision and provides insurers with further clarity on their investigatory obligations and reasonableness determinations in PIP matters.  Insurers remain responsible for determining whether to deny, limit or terminate medical benefits where the insurer determines treatment was not reasonable or necessary. Insurers are also still required to conduct a reasonable investigation and develop reasonable standards to promptly investigate claims.

As the Schiff decision makes clear, insurers can safely continue to rely on databases such as the FAIR Health database to determine whether a provider’s charges are reasonable and are not required to individually investigate and vet each provider when making that determination as part of that process.

The attorneys at Lether Law Group have in excess of thirty-one years’ experience in defending and advising insurers on the handling of PIP claims. This experience includes handling claims and litigating insurance disputes in the state of Washington. Please do not hesitate to contact our office if you have any questions regarding the Schiff decision or any other insurance matter.

[1] The FAIR Health database was identified as an “independent, nonprofit, medical claim database.”

Oregon Supreme Court Unilaterally Creates “Negligence” Cause of Action Against Insurers

On December 29, 2023, the Oregon Supreme Court effectively created new bad faith liability exposure for insurers doing business in Oregon when it issued its opinion in Moody v. Or. Cmty. Credit Union, 371 Ore. 772, 2023 Ore. LEXIS 692 (2023). In Moody, an insured sued a life insurance company for breach of contract and negligence based on a denial of a claim for life insurance proceeds.

The Plaintiff’s husband was the named insured under a life insurance policy and was accidently shot and killed. At the time of his death, the decedent had marijuana in his system. The Plaintiff filed a claim, and the defendant insurer initially denied the claim because the decedent’s death purportedly fell within an exclusion for deaths caused by or resulting from being under the influence of a narcotic or other drug.

The Plaintiff brought suit alleging that the death was not caused by or resulting from the use of any drug. She alleged claims for breach of contract, breach of the implied covenant of good faith and fair dealing, and negligence. Plaintiff sought both economic and non-economic damages including emotional distress damages. The extra-contractual claims were dismissed by the trial court and proceeded to an appeal. The Court of Appeals reversed the trial court’s dismissal of the negligence claim and the Supreme Court accepted direct review.

On review, the Supreme Court framed the primary question as whether the Plaintiff could pursue a negligence per se claim. The Court clarified that, in Oregon, a negligence per se claim is shorthand for a negligence claim that otherwise exists where the standard of care is set forth in a statute or rule and violation of the statute or rules raises a presumption of negligence.

Under that framework, the Court first examined whether the Plaintiff had a legally protected interest sufficient to subject the Defendant to liability for emotional distress damages. In determining that she did, the Court examined ORS 746.230 (Oregon’s Unfair Claim Settlement Practices statute). While acknowledging that the statute did not create an independent cause of action, the Supreme Court nevertheless found as follows:

We find that the statue provides explicit notice to insurers of the conduct that is required and, in requiring insurers to conduct reasonable investigations and to settle claims when liability becomes reasonably clear, does so in terms that are consistent with the standard of care applicable in common claw negligence cases.

Moody, 2023 Ore. LEXIS 692 at *41.

The Court went on to hold that permitting a common law negligence claim could further the statute’s purpose by deterring insurers from engaging in prohibited conduct. The Court went on to find that allowing emotional distress damages would not place an undue burden on the Defendant because insurers are in a relationship of mutual expectations with insureds and that the insurer could reasonably foresee that failing to exercise reasonable care in the handling of the relationship could result in emotional harm. Finally, the Court held that the claimed harm was of sufficient importance under public policy to justify allowing the claim to proceed. The Court’s ultimate conclusion was stated as follows:

Considering all of those factors, and not relying on any one of them alone, we conclude that the insurance claim practices that ORS 476.230 requires and the emotional harm that may foreseeably occur if that statute is violated are sufficiently weighty to merit imposition of common-law negligence and recovery of emotional distress damages.

Moody, 2023 Ore. LEXIS 692 at *51.

While the Court cautioned that its conclusion would not make every contracting party liable for negligence that causes emotional harm, the holding is extremely concerning and problematic for insurers. In fact, the holding may effectively overturn long-standing Oregon case law holding that insurers are not liable in tort for the handling of an insurance claim. See, e.g., Farris v. U.S. Fid. and Guar. Co., 284 Ore. 453, 587 P.2d 1015 (1978) (Farris II). This issue was recognized in the Moody dissent as follows:

The majority’s analysis creates uncertainty about the remaining precedential effect of Farris II. If the majority means to distinguish Farris II on its facts, then courts may still rely on Farris II as rejecting tort liability for third-party insurers that have denied coverage in bad faith, which were the facts presented in that case. On the Other hand, if the majority is distinguishing Farris II based on the pleadings or based on the legal theory that the plaintiffs asserted in that case, then Farris II might have no precedential effect in any case styled as a negligence claim.

Moody, 2023 Ore. LEXIS 692 at *78 n.7.

The full nature and impact of the Moody decision will likely remain unknown until the Oregon Supreme Court has had the opportunity to further clarify or refine its holding in subsequent cases. As it stands, insurers in Oregon now potentially face liability for general damages (and potentially other alleged consequential damages) in tort as long as those claims are styled as negligence claims. Effectively, the Oregon Supreme Court has created bad faith liability for insurers based on a negligence standard of proof. This reflects a substantial increase in exposure for insurers doing business in Oregon especially when one considers that the majority of jurisdictions require a higher burden of proof for bad faith claims (i.e. unreasonable, frivolous, or unfounded denial of benefits).

The attorneys at Lether Law Group have in excess of thirty-one years’ experience in advising insurers on the handling of extra-contractual claims. This experience includes handling claims and litigating insurance disputes in the state of Oregon. We have several attorneys licensed in Oregon and actively litigating coverage and extra-contractual claims in that jurisdiction. Please do not hesitate to contact our office if you have any questions regarding the Moody decision or any other insurance matter.


Logo for Letber Law Group

Wintertime Property Claims

It is the Season. Not just for the Holidays but also for winter storm property damage claims.

The volume of commercial and homeowner property claims typically increase during the winter months. This is due in large part to winter weather conditions. The typical types of winter claims include:

Frozen Pipe Claims: Exposed pipes will freeze. These types of claims trigger language in almost all property policies, including coverage and exclusions involving claims arising from the sudden accidental failure of plumbing systems due to freeze conditions. Typically, the policy language requires the building owner to take precautions to drain water lines or prevent against such freezing in order to have coverage.

Storm Drain Backup Claims: Heavy rains or snow melt can lead to storm drain back ups and flooding. These claims are typically covered but may be subject to a specific and lower policy limit.

Wind Driven Rain Claims: Particularly for those who live in the Northwest, we are used to heavy periods of rainfall often accompanied by strong wind conditions. A typical wind-driven rain claim may involve sudden and accidental leakage into a building as well as long-term water and decay damage. In Washington, wind-driven rain claims may be covered in the absence of weather exclusionary language.

Wind Claims: Winter storms usually bring high wind conditions. This can result in the failure of power utilities, downed trees, roof damage, etc. Depending on the policy language, these types of claims are typically covered.

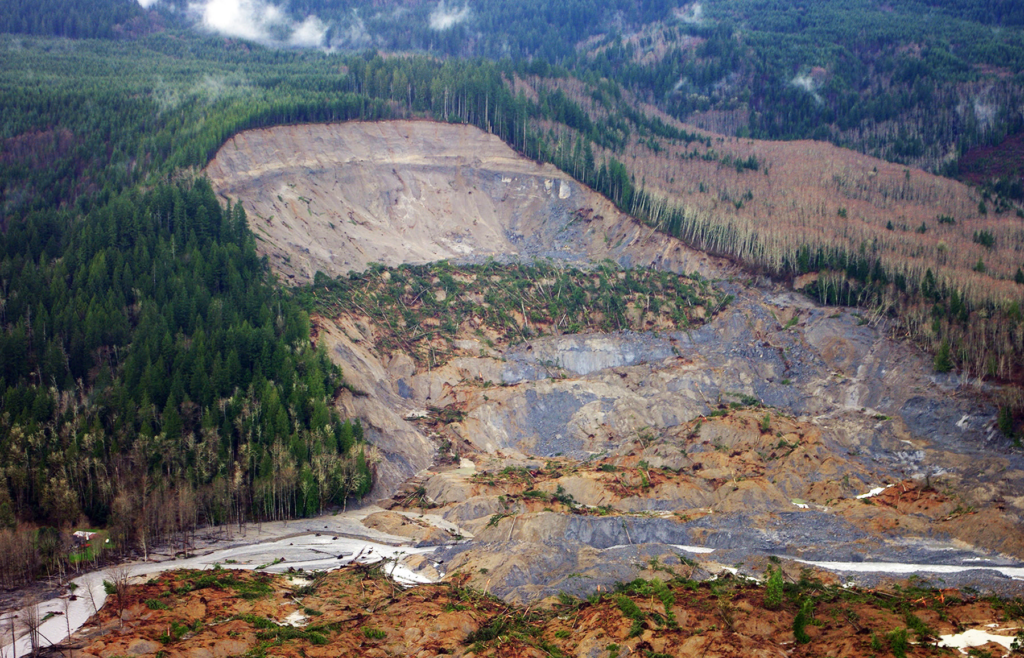
Landslides: Heavy rainfall and wind conditions can contribute to saturated soils. This often results in landslides, particularly in the Northwest. Landslide events are typically excluded from coverage unless landslide coverage is expressly provided for.

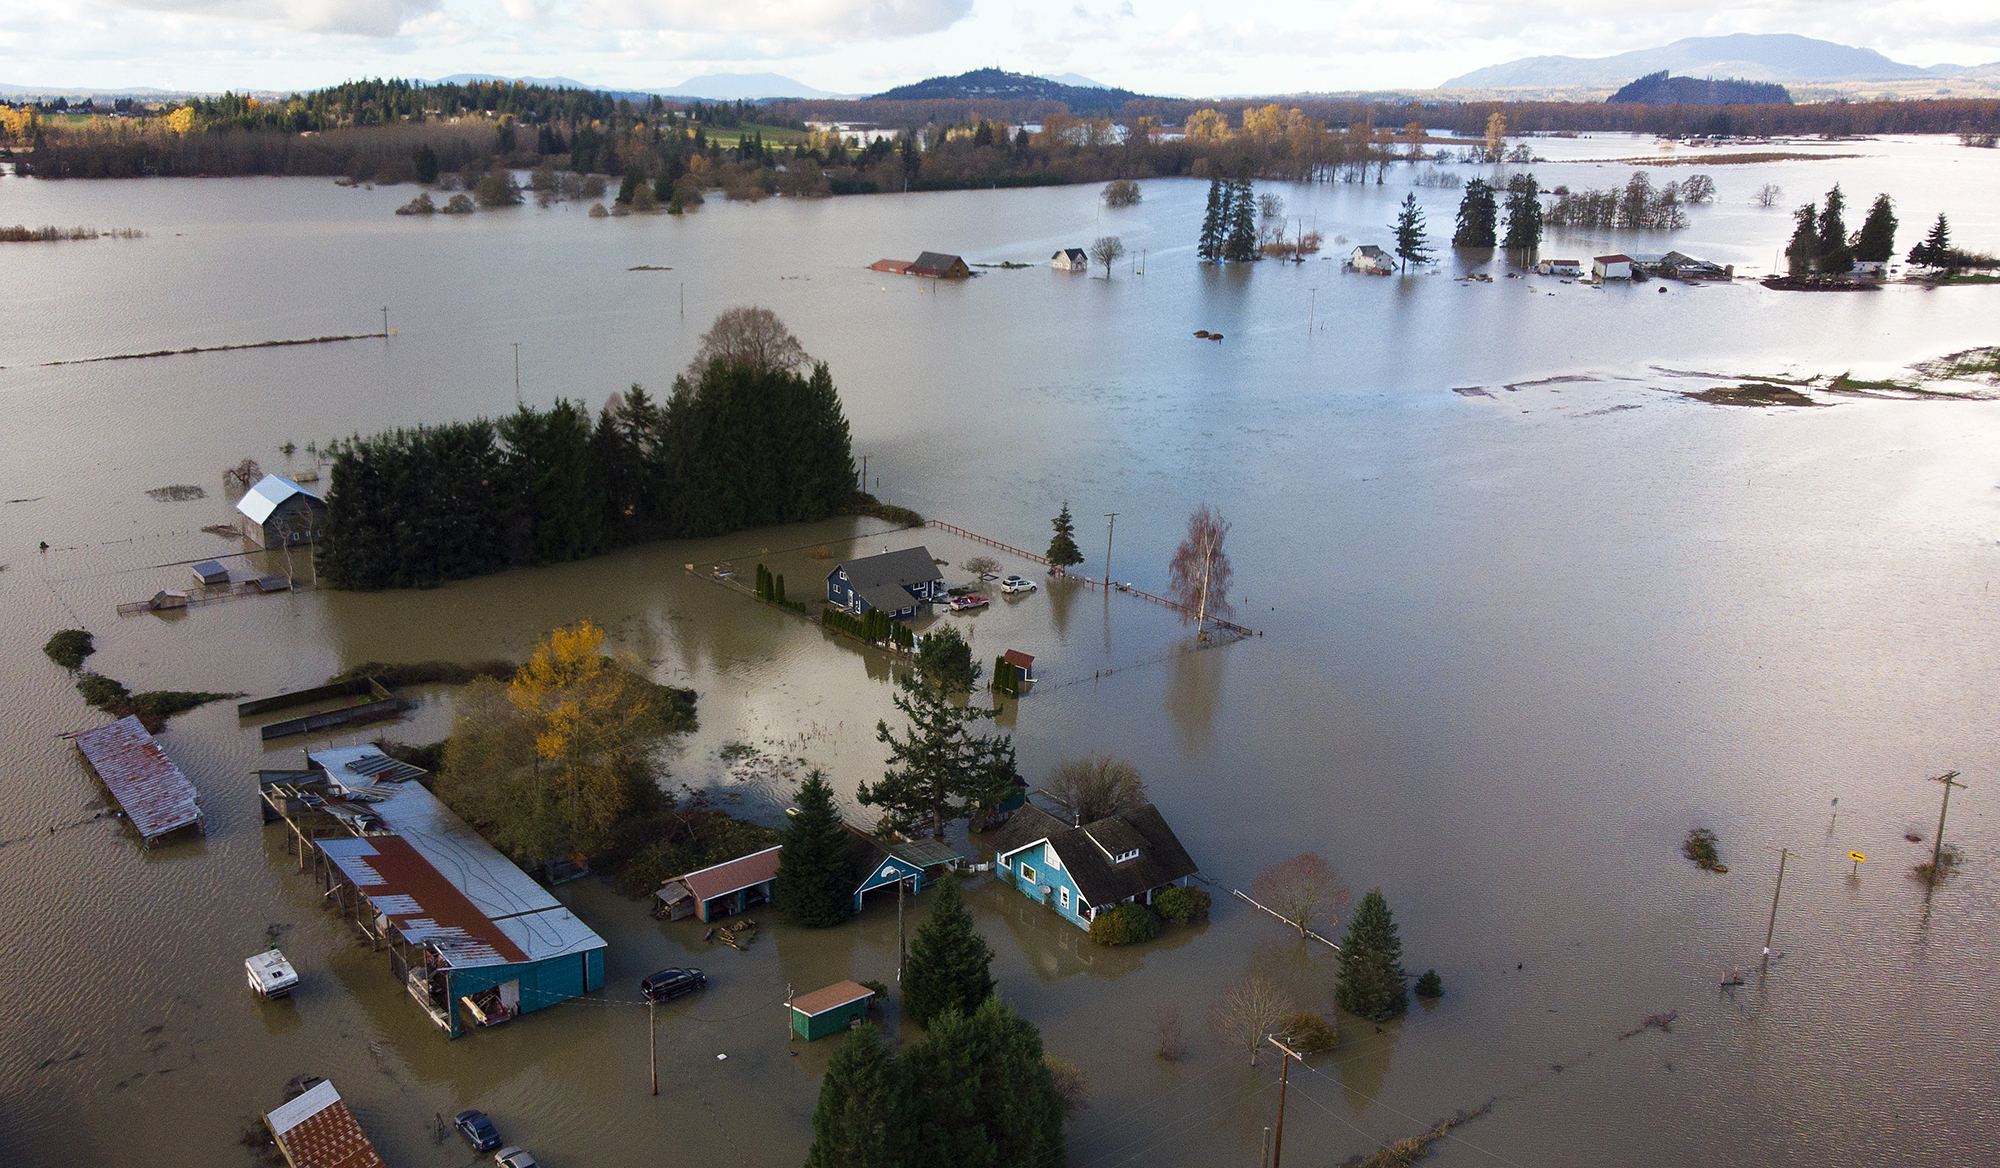
Flood Claims: Heavy rainfall and snowmelt can lead to both river and tidal flooding. In addition to river overflow, strong King tides can result in oceanic saltwater flooding from tidal bodies of water. In the absence of express flood coverage, most surface water and floodwater claims are excluded from coverage. If a building owner has flood insurance, that insurance is typically paid by an insurer through the Federal Emergency Management Agency (FEMA) under the National Flood Act. There are severe restrictions on what is allowed to be recovered under the National Flood Insurance Act. For example, in a FEMA flood claim, there is no right to policy appraisal, no right to trial by jury, and no recovery of extra contractual or bad faith claims.


Once again, every policy is different. However, those building owners who are confronted with severe winter weather should review their policies and understand what is and what is not covered.

Lether Law Group has handled winter storm-related claims throughout the Northwest. This includes major catastrophes such as the Oso landslide, the Skagit River valley flooding, the Kingston and Perkins Lane landslide losses, and thousands of water intrusion and wind-driven rain type claims. Tom Lether has been directly involved as counsel retained through FEMA to litigate claims involving flood losses under the National Flood Insurance Act.

If you have questions in regard to winter storm damage claims, please feel free to info@letherlaw.com or (206) 467-5444.


WASHINGTON COURT HOLDS THAT USE OF A FORMULAIC APPROACH TO DETERMINE REASONABLENESS OF PROVIDER CHARGES IS A VIOLATION OF THE CONSUMER PROTECTION ACT

The Washington State Consumer Protection Act (CPA) prohibits the use of unfair methods of competition and unfair or deceptive acts or practices in the insurance industry. The Washington Supreme Court has held that in order to prevail on a private CPA claim, a plaintiff must establish 5 elements: (1) an unfair or deceptive act or practice, (2) occurring in trade or commerce, (3) with public interest impact, (4) an injury to the plaintiff’s business or property, and (5) causation. Hangman Ridge, 105 Wn.2d at 780. While this case law provides some guidance, it is silent as to whether a particular practice is “unfair” or “deceptive” under the CPA.

On November 28, 2022, the Washington Court of Appeals further defined what constitutes an unfair or deceptive practice under the CPA. The case of Stan Shiff, M.D., Ph.D. v. Liberty Mutual Fire Insurance Co., et. al, dealt with whether an insurer violates the CPA by “relying solely on a mechanistic, formulaic approach” to determine the reasonableness of a medical providers bill. The Court held this practice to be a violation of the CPA.

Shiff arises out of a dispute between a medical provider and an insurer regarding payment of medical bills. Stan Shiff, M.D., Ph.D, is a neurologist who treated patients insured by Liberty Mutual Fire Insurance Company. Shiff submitted bills to Liberty Mutual for his treatment of its insureds, however Liberty Mutual refused to pay these bills in full. Instead, Liberty Mutual used its “80th percentile practice” to determine whether these bills were reasonable and warranted full payment. In using its 80th percentile practice, Liberty Mutual determined that payment of the full amount of the charges submitted by Shiff was not reasonable. As such, Liberty Mutual reduced its payment on the bills to the 80th percentile amount.

In using the 80th percentile practice to determine whether payment of the full amount of a provider’s bill was reasonable, Liberty Mutual relied solely on the FAIR Health Database. The FAIR Health database “compares billed charges to the charges submitted by other medical providers within the same broad geographical area.” Liberty Mutual relied on this database to determine that Shiff’s charges were unreasonable, as the exceeded the 80th percentile of charges in the FAIR Health database for the same services in the same broad geographical area.

With regard to liability under the CPA, Shiff relied on the precedent in Folweiler Chiropractic, PS v. Am. Fam. Ins. Co., 5 Wn. App. 2d 829, 429 P.3d 813 (2018). In Folweiler, the Court established that an insurer had a duty to conduct an individualized investigation, including the duty to evaluate the identity, background, credentials, experience, or any personal characteristic of the individual provider in evaluating the reasonableness of the bill. Folweiler, 5 Wn. App. 2d at 838. The Court found in favor of Shiff, ruling that it was undisputed that Liberty Mutual did not conduct the kind of individualized investigation as required by Folweiler.

Based on Liberty Mutuals violation of its duty to conduct an individualized investigation, Shiff argued Liberty Mutual’s 80th percentile practice violated the CPA. Liberty Mutual disagreed asserting that because the practice was approved by the Office of the Insurance Commissioner (OIC), it was not a violation of the CPA. Liberty Mutual asserted that, even if the 80thpercentile practice constituted an unfair practice, it is exempt from CPA liability pursuant to the statutes regulated industries exemption, RCW 19.86.170. Liberty Mutual argued that because insurers are prohibited from obtaining regulatory approval of its policies prior to issuing them, conduct arising from those policies is “permitted” pursuant to the CPA’s exemption provision. The Court rejected this argument, finding “Liberty Mutual’s 80th percentile practice is indistinguishable from the practice we held unlawful in the Folweiler decision.” Additionally, the Court found Liberty Mutuals exemption provision argument unconvincing, noting that it is contrary to the “legislature’s clear mandate” that violations of the insurance regulations are subject to CPA liability. The court clarified that to agree with Liberty Mutual would “exempt broad swaths of insurer conduct from CPA liability, in direct contravention of our legislatures express intention that such conduct be subject to our states’ consumer protection law.” Therefore, the Court rejected Liberty Mutual’s reading of the CPA exemption provision.

As a result of the Shiff decision, use of any formulaic approach to determining the reasonableness of a provider’s medical bill constitutes a violation of the Washington Consumer Protection Act. Pursuant to the Folweiler and Shiff decisions, insurers are required to conduct an individualized investigation before reducing a medical bill.

Lether Law Group currently represents multiple insurers in coverage litigation in state and federal courts in Washington involving claims under CPA. If you have questions about the implications of Shiff or general questions in regard to pending insurance claims and compliance with Washington insurance law, please feel free to contact our office.